
Private credit secondaries: Capturing opportunity through market cycles
As the private credit secondaries market grows in scale and sophistication, specialist funds are becoming an increasingly relevant portfolio tool. They can provide institutional investors with diversified, seasoned exposure, complement primary private credit allocations, and extend established private equity secondaries programs into credit. At a time when slower repayments, portfolio rebalancing, and liquidity needs are bringing more assets to market, the strategy may also offer an attractive way to deploy capital selectively through a period of greater credit dispersion.
Private credit secondaries: A market entering its next phase
Over the past decade, private credit has evolved from a specialist segment into an increasingly important component of institutional portfolios. On its traditional definition,1 global private credit assets under management are estimated at approximately $2.3 trillion in 2025 and forecast to reach approximately $4.5 trillion by 2030.2 Broader estimates are materially higher when adjacent segments such as specialty finance and asset-backed finance are included.
As the primary private credit market has expanded and successive vintages have matured, it has created a growing stock of seasoned fund interests and underlying loans that can support liquidity, portfolio-rebalancing, and continuation solutions. This, in turn, has provided the foundation for the rapid development of the private credit secondary market.
Although the segment remains relatively small within both private credit and the broader secondary market, transaction volume has increased eightfold since 2020, reaching $20 billion in 2025—an 83% increase from 2024— and could exceed $50 billion over the next two to three years,3 supported by significant room for further penetration: secondary volumes remain below 1% of the private credit primary market, compared with 2–3% in private equity.4
Figure 1: Private credit secondaries transaction volume and LP-led/GP-led share (USD billions)
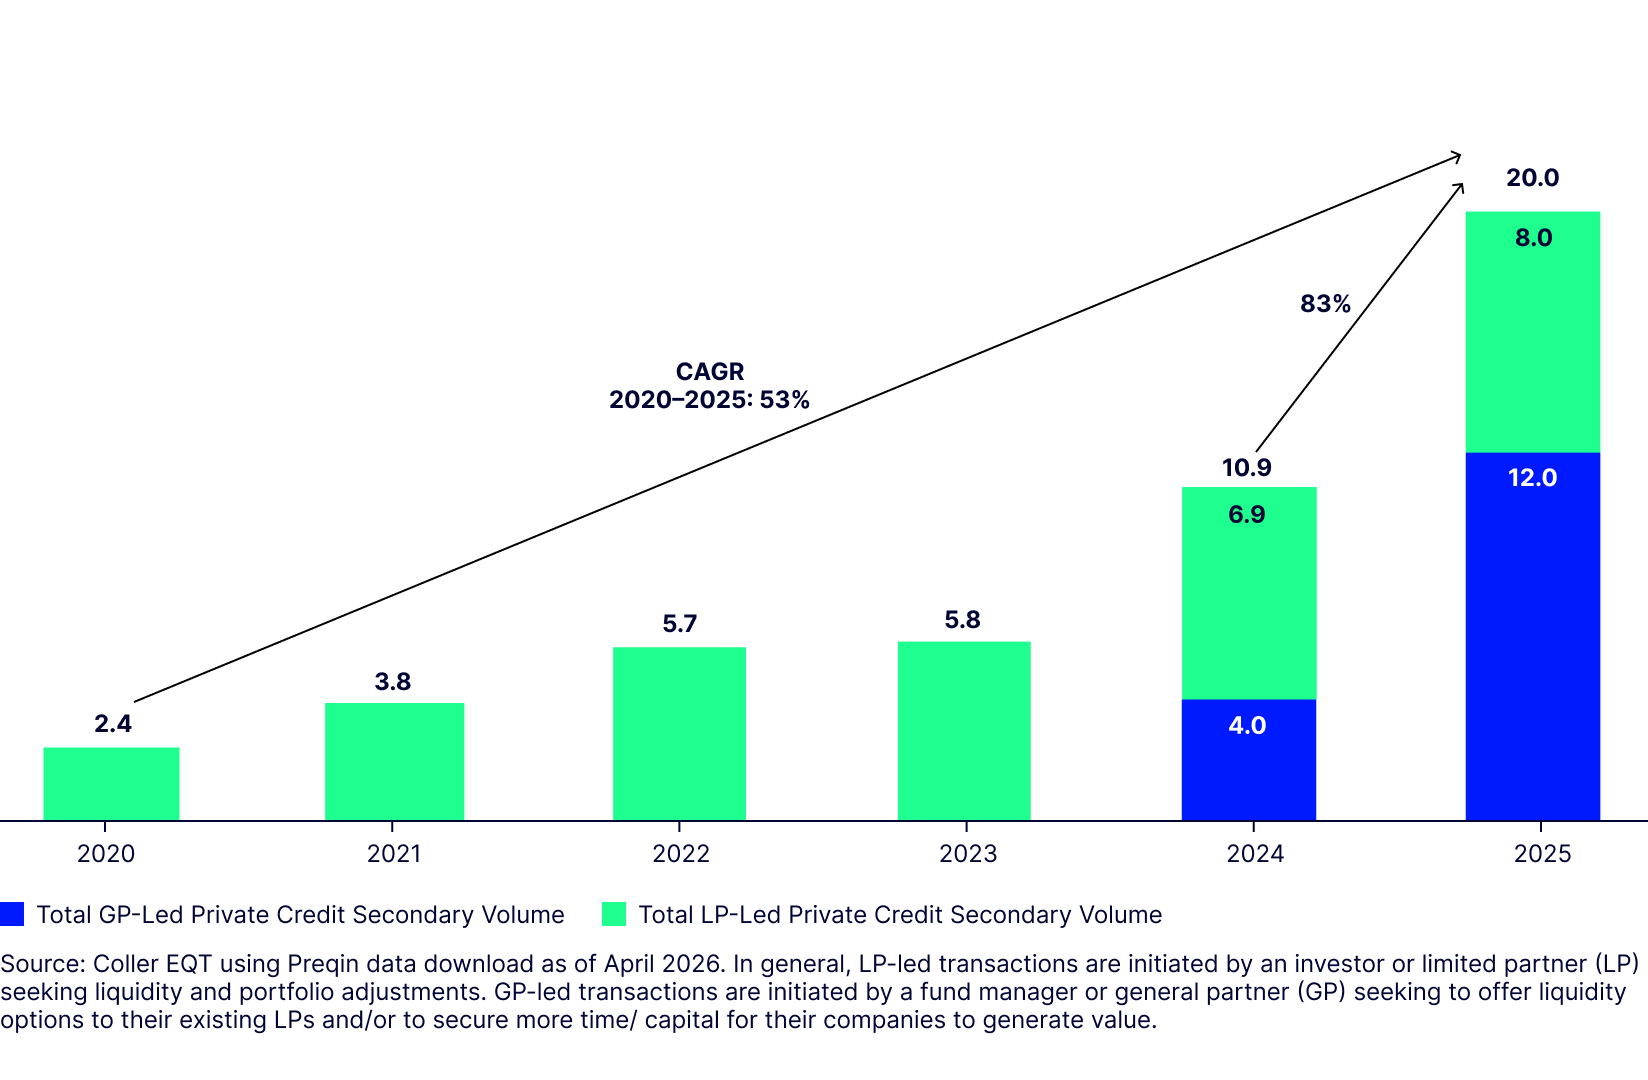
The rapid growth of the market has been supported by three interconnected factors: (i) a larger addressable market as private credit has expanded and matured, where secondaries can play the role of an additional exit route as they do in private equity, (ii) stronger seller motivations, driven by slower repayments, portfolio-management needs, and regulatory or balance-sheet constraints, and (iii) improved execution capacity, underpinned by greater specialist capital, more established valuation practices, and deeper intermediation.
The market’s increasing maturity is also reflected in the emergence and rapid growth of large GP-led opportunities in 2025.
Figure 2: Drivers of private credit secondaries growth
| A larger addressable market |
|
|---|---|
| Stronger seller motivations |
|
| Improved execution capacity |
|
Source: State Street Investment Management, Coller EQT, Ares. Non-exhaustive list of growth drivers for illustrative purposes only.
For an investor in a private credit secondary fund, the significance is not the forecast alone: a deeper market can give specialist managers a broader range of sellers, transaction types, and portfolio entry points from which to construct a diversified fund.
The distinctive benefits of private credit secondaries
In addition to the benefits shared with private equity secondaries—including diversification, faster deployment, lower blind-pool risk, more efficient portfolio construction, and discounted entry through secondary pricing and structuring, as detailed in Secondary funds as a strategic portfolio tool: From liquidity to program implementation—private credit secondaries offer characteristics derived specifically from the contractual nature of debt. These include:5
- Recurring income, as the underlying loans may generate interest during the holding period.
- Potentially earlier and more visible cash flows, supported by interest payments, amortization, and contractual maturities.
- A shorter expected duration, as seasoned credit portfolios may already be amortizing or approaching maturity and may therefore return capital sooner than private equity secondary portfolios.
- Structural downside protection through seniority, collateral, covenants, and lender remedies.
- Returns that may be less dependent on company exits.6
When combined with disciplined underwriting, purchasing assets at a discount to their re-underwritten value may provide additional return potential through discount accretion, subject to underlying credit performance and repayment outcomes.
As a result, private credit secondaries may provide investors with a more income-oriented and capital preservation-focused complement to their existing private markets allocation.
A strategic entry point in a period of credit dispersion: Why now?
The investment case rests on the strategy’s potential to improve both the construction and implementation of an investor’s private credit allocation. A private credit secondaries fund should not be viewed simply as a source of discounted assets. Its more enduring role is to combine diversified access, seasoned credit exposure, deployment efficiency, and differentiated cash-flow characteristics within a single allocation.
Timing is also relevant. With appropriate safeguards, private credit secondaries can offer institutional investors a way to invest through market cycles, as uncertainty in the primary credit market may create opportunities in the secondary market. Slower repayments, portfolio-management needs, and liquidity pressure can bring a wider range of portfolios to market, including high-quality, performing assets sold for reasons unrelated to borrower distress. Recent redemption pressure in certain semi-liquid and non-traded private credit vehicles, including business development companies, may add to this supply. These conditions can benefit buyers with patient, committed capital. Sellers seeking immediate liquidity may be prepared to accept larger discounts, while specialist buyers can be more selective on price, documentation, and credit quality.
At the same time, greater dispersion in borrower quality and repayment outcomes increases the importance of loan-level diligence. The opportunity may therefore favor managers with broad sourcing networks, deep credit expertise, and the ability to assess opportunities across both LP-led and GP-led transactions.
For investors, this may create a window in which secondary-market supply and sellers’ liquidity needs are growing faster than the capital available to absorb them. Investors that establish commitments before supply-and-demand conditions normalize may provide managers with greater flexibility to deploy selectively. The objective is not to predict a broad credit downturn, but to provide an experienced manager with the capital and time to invest through a period of greater dispersion.
From allocation rationale to portfolio implementation
The role of the allocation should be defined by the investor’s starting point, existing private credit exposure, and portfolio objective. For some, the fund can provide a diversified entry point into private credit. For others, it can complement primary funds by adding mature assets, multiple origination years, and a different cash-flow profile. Investors should therefore determine what problem the allocation is intended to solve before deciding its size and funding source.
In practical terms, private credit secondaries can fulfil three principal roles in an allocator’s portfolio:
- An alternative entry point to private credit primaries—for investors that have not yet allocated to the asset class or have limited commitment capacity, private credit secondaries can provide exposure through diversified portfolios of managers, credit strategies, geographies, and transactions.
- A complement to an established primary private credit allocation—adding mature assets, broader origination-year exposure, and potentially earlier income and principal distributions.
- An extension of an established private equity secondaries program—allowing investors to apply an existing secondaries allocation framework to credit while introducing distinct contractual cash flows and return drivers, downside protections, and underwriting considerations.
Where the selected manager also has established GP-led capabilities, the allocation may provide additional diversification by transaction type and underlying asset exposure.
Figure 3: Portfolio applications of private credit secondaries
| Investor starting point | Potential role of a private credit secondaries fund | Portfolio consideration |
| New or underweight private credit allocation | Provide diversified, seasoned exposure through a single commitment and shorten the initial portfolio ramp-up period | Use as an entry allocation alongside a multi-year primary commitment plan rather than assuming it fully replaces vintage diversification |
| Established primary private credit program | Add mature assets, broaden origination-year exposure and potentially generate earlier income and principal distributions | Assess overlap by manager, borrower, sponsor, sector and underlying economic exposure on a look-through basis |
| Established private equity secondaries program | Extend an existing secondaries allocation into credit, adding contractual income, shorter-duration assets and a different risk-and-return profile | Determine whether private credit secondaries should sit within the existing secondaries allocation, the private credit bucket or a broader opportunistic allocation |
| New to GP-led transactions | Gain selective exposure to continuation vehicles and other manager-led liquidity solutions through a specialist with relevant underwriting and execution capabilities | Scrutinise valuation, asset selection, governance, conflicts, alignment, process integrity and the manager’s ability to underwrite concentrated exposures |
| Concentrated manager or strategy exposure | Broaden the portfolio across managers, strategies, geographies, origination years and transaction types | Set explicit diversification objectives and concentration limits, including at borrower and sponsor level |
| Need for deployment and cash-flow efficiency | Accelerate invested exposure and introduce portfolios that may already be generating income and repayments | Model capital calls, interest income, amortisation, principal repayments, extensions and downside scenarios |
| Limited internal execution resources | Delegate sourcing, loan-level underwriting, valuation, legal execution and monitoring to a specialist manager | Place greater weight on manager selection, transparency, reporting rights and workout capabilities |
Source: State Street Investment Management. Non-exhaustive illustration of potential portfolio applications for illustrative purposes only.
The allocation process for a private credit secondaries fund broadly mirrors that for private equity secondaries: investors should define the purpose of the allocation, understand the fund’s strategy mix, select the right manager, and integrate the commitment into the broader portfolio.
Given the technical characteristics of the underlying investments and the market’s still-developing nature, understanding the strategy mix and selecting the manager are particularly important. Investors should develop a clear view of the fund’s intended exposure across performing senior credit, opportunistic and stressed investments, asset-based finance, real asset credit, and other sub-strategies, as each carries a distinct risk, return, and cash-flow profile.
While manager selection is critical across all fund strategies, it is especially consequential in private credit secondaries. As a smaller and comparatively less mature market, the universe of managers with deep, tested capabilities remains limited. Investors should therefore assess expertise across sourcing, loan-level underwriting, valuation, transaction execution—including newer GP-led structures—portfolio construction, monitoring, and workouts.
Sourcing capabilities also warrant careful scrutiny. As the market has matured and attracted greater interest, a growing number of managers historically focused on primary private credit have expanded into secondaries. While these firms may bring relevant credit expertise and established market relationships, their access to transactions may be constrained where counterparties perceive them as competitors—for example, when seeking access to GP-led opportunities involving another lender’s assets or when bidding for LP-led portfolios containing exposure to competing managers.
Rigorous manager due diligence—covering both investment capabilities and the breadth, quality, and independence of the sourcing network—is therefore central to successful implementation.
Key considerations before committing
These potential benefits should be assessed against several important considerations, including illiquidity, manager dispersion, transaction dynamics, and fees. Specifically:
- Although seasoned portfolios may generate earlier distributions, commitments remain long term and repayment timelines can change.
- Outcomes may vary materially across managers, reflecting differences in sourcing, loan-level underwriting, purchase discipline, and workout capabilities. Sellers may also possess better information on weakening assets, making independent diligence essential.
- Reported valuations can lag underlying credit developments, so any discount should be measured against a re-underwritten value rather than viewed as an automatic margin of safety.
- Diversification warrants particular attention in private credit, where upside is generally capped but losses can be material. Unlike in private equity, where strong outperformance from one investment may offset losses elsewhere, gains on a performing loan are unlikely to compensate fully for a significant impairment in another.
- Investors should therefore look through fund-level diversification to assess concentration and correlated exposures across borrowers, sponsors, sectors, geographies, and economic drivers. In GP-led transactions, they should also scrutinize governance and alignment, as the incumbent manager may influence asset selection, valuation, and process. Ultimately, expected returns should be evaluated net of fund expenses, carried interest, financing costs, leverage, and potential credit losses.
A timely but selective allocation opportunity
Private credit secondaries are becoming an increasingly relevant portfolio tool as the market matures and liquidity needs create a broader supply of seasoned assets.
For institutional investors, specialist funds can provide diversified exposure, faster deployment, reduced blindpool risk, and potentially earlier cash flows—while giving experienced managers the flexibility to invest selectively through periods of credit dispersion.
Implementation remains critical: investors should define the allocation’s portfolio role, understand the underlying strategy mix, and select managers with proven sourcing, underwriting, execution, and workout capabilities.
Used thoughtfully, private credit secondaries can provide a differentiated, income-oriented complement to both primary private credit and private equity secondaries allocations.