
Monthly Fund Commentary State Street Floating Rate Fund
Overview
In September, the State Street Floating Rate Fund returned 0.34% (net), underperforming the benchmark by 0.02%.1
Australian money markets moved steadily higher through September, with the RBA raising the cash rate by 25bp to 4.60% at its 29 September meeting, as expected, with the Board pointing to upside inflation risks from the broadening Middle East conflict and higher energy prices. Markets were braced for CPI that wasn't expected to ease, and annual CPI delivered, rising to 4.0% the following day. Bill yields had been trending higher through the month, with six-month BBSW peaking at 5.15% on 29 September before easing slightly into month end. The BBSW curve shifted higher in a broadly parallel move, with one-month BBSW rising from 4.30% to 4.54%, while three-month BBSW rose from 4.55% to 4.77% and six-month BBSW increased from 4.88% to 5.12%.
September saw a slower pace of primary issuance across the FRN market, with approximately A$4.55 billion of new supply added across 6 issuers. This included ING, Nationwide and Mizuho, who accounted for around $3.3 billion between them, issuing between $1.0 billion and $1.3 billion each, with the AAA-rated ING and Nationwide deals pricing at BBSW +60 for the 2031. The fund added to selected existing exposures via secondary market trading, taking advantage of wider spreads to enhance the portfolio's yield, which rose to 5.75% from 5.42%, while maintaining its defensive risk profile and liquidity characteristics.
The State Street Floating Rate Fund has outperformed its benchmark over all time periods net of fees, delivering +0.63% of alpha over the past 12-months, +1.04% p.a. over the past 3-years and +0.86% p.a. since inception.
Looking Ahead
Market Update and Outlook
Australian bonds continued to sell off in September, with losses the largest of the quarter. The Bloomberg AusBond Treasury 0+ Yr Index returned -0.88%, while the Bloomberg AusBond Composite 0+ Yr Index returned -0.86%. Performance was weighed down by a sharper rise in sovereign yields, with duration detracting across most of the curve. Carry helped cushion the impact at the front end, but longer-dated bonds remained more exposed to the increase in yields.
In a much anticipated unanimous decision, the RBA raised the cash rate by 25bp to 4.60% at its September meeting, marking its fourth increase this year. The Board said that "some of the upside risks flagged in August are materialising". The broadening Middle East conflict has pushed global energy prices well above the assumptions in the August forecasts, with higher fuel costs flowing through to other prices, and recent inflation outcomes coming in stronger than expected. Domestic capacity pressures and the elevated short-term inflation expectations added to the case. On activity, growth in the June quarter was slightly stronger than expected, while consumer spending undershot and the labour market eased broadly as expected with the participation rate rising. The Board flagged the housing downturn as a source of uncertainty, with prices falling in most capital cities and new housing loans declining noticeably. The Board retained its tightening bias and said they will raise the cash rate further "if needed". However, the Governor's press conference pointed to a near-term pause, describing policy as restrictive and said much of the 100bp of tightening delivered this year is still to flow through.
The outlook shifted over the quarter, with the RBA moving earlier than we expected as upside risks to inflation began to materialise. Looking ahead, markets are pricing a ~30% chance of a further hike at the November meeting and a full 25bp hike priced in by H1'27, and the cash rate currently expected to peak around 4.85%. With policy now restrictive and much of this year's tightening still to flow through, we believe the RBA will remain on hold in November, with Q3 CPI and the September labour force report the key releases to watch. A stronger than expected trimmed mean result could bring November back into play, while further weakness in household spending and the labour market would support an extended pause.
Bottom Line
"The only function of economic forecasting is to make astrology look respectable." — John Kenneth Galbraith
Galbraith's point is that even well-resourced forecasters can get the future wrong, and September showed it. By the September meeting, the RBA's August forecasts had been overtaken. The Board modelled its outlook on the basis that oil prices would return to ~$70 a barrel in relatively short order, yet this was not the case as global energy prices remained at much higher levels than it had assumed, forcing its hand. This shows it pays to be prepared for various outcomes and FRNs can offer this. An investor positioned for only one has to be right on timing, and being wrong can be expensive.
The higher energy prices impacted inflation and were a prime reason the RBA moved again in September (see Figure 1). Headline CPI rose back to 4.0% in August, up from a low of around 2% in late 2024, while trimmed mean inflation held at 3.6%. With both above the top of the target band, the RBA decided it could not wait any longer. The statement said some of the upside risks flagged in August were now materialising, with higher energy prices flowing through to other prices and capacity pressures still in the system. The Governor described policy as restrictive and said much of the earlier tightening is still to flow through, but it is hard to be confident that 4.60% is the peak for as long as inflation keeps moving the wrong way.
Given the current hiking environment, we decided to look at how FRNs have performed against fixed-rate bonds and found FRNs have generally come out ahead. We used returns from the Bloomberg AusBond Credit FRN 0+ Yr Index to represent FRNs and the Bloomberg AusBond Composite 0+ Yr Index to represent fixed-rate bonds, assessing the performance over the current and previous hiking cycles going back to 1999. Figure 2 shows FRNs outperformed fixed-rate bonds in three of the four previous tightening cycles, averaging an annualised return of 5.60% for FRNs, against 4.58% for fixed rate bonds. This cycle has followed a similar pattern, with FRNs returning an annualised 4.86% since rates began rising in February, compared with 0.82% for fixed-rate bonds. The gap widened in September, when FRNs returned 0.37% over the month while fixed-rate bonds fell -0.86%. FRNs can be a good investment during rate hiking cycles, as income rises with the cash rate and their minimal duration means they carry very little interest rate risk. If inflation remains sticky and the RBA has to hike further, investors will benefit. If the RBA pauses here, FRNs still earn income at the current higher level, making them a sensible way to stay invested in fixed income while the outlook for inflation and the cash rate remains uncertain.
Figure 1: Australian Headline CPI increases to 4.00%
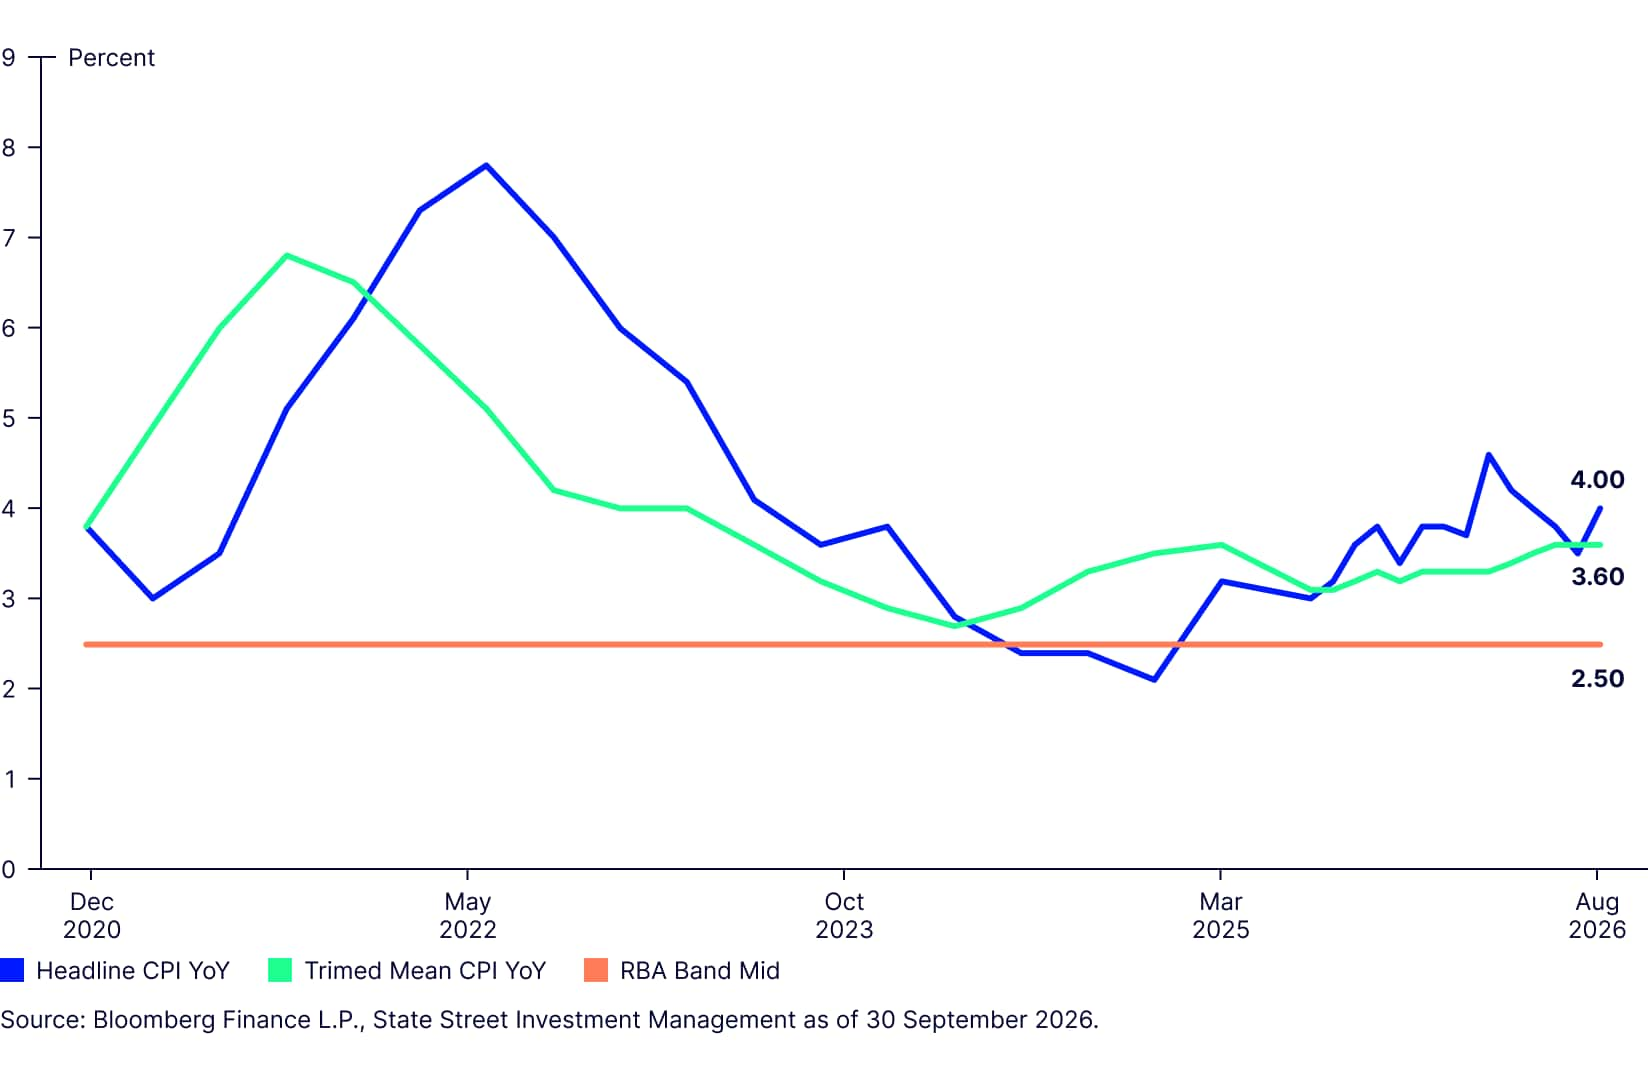
Figure 1 shows headline CPI rising back to 4.0% in August 2026 after a low of about 2.1% in December 2024. Trimmed mean inflation has held at 3.6% and hasn't been near the 2.5% target midpoint since early 2024. Both measures are well above the midpoint, which is why the RBA tightened again in September.
Figure 2 shows FRNs outperformed fixed-rate bonds in three of the four previous tightening cycles, averaging an annualised 5.60% against 4.58%. The gap was widest in May-22 to Nov-23, when FRNs returned 3.89% while fixed-rate bonds lost 0.23%. The exception was Nov-99 to Aug-00, when fixed-rate bonds came out ahead (7.06% against 6.65%).